An AAC plant should plan enough operating cash to cover the gap between paying for production and collecting payment for accepted blocks during ramp-up. Build a weekly cash forecast from realistic production yields, stock movements, customer credit and supplier payment dates. The required reserve depends on the deepest cumulative cash shortfall and credible delays, rather than a fixed percentage of equipment cost.
Follow the Cash Before Following the Profit
A plant can report sales while its bank balance continues to fall. Materials, wages and utilities may be paid before blocks are accepted, invoiced and collected. Early production instability can widen that gap because additional cash goes into trials, rejected batches and slower dispatch.
Distinguish working capital from total project funding. An accounting working-capital measure considers current assets and current liabilities, while a ramp-up cash plan shows when actual payments and receipts occur. Neither should be used as a substitute for a separate schedule of equipment instalments, construction payments and financing obligations.
Use the AAC plant investment cost framework to separate project costs from operating requirements. A cash forecast can include both for funding purposes, but each payment must appear once. Calling an equipment deposit working capital does not make the project need less money.
Build the Opening Position From Physical Quantities
Raw Materials and Consumables
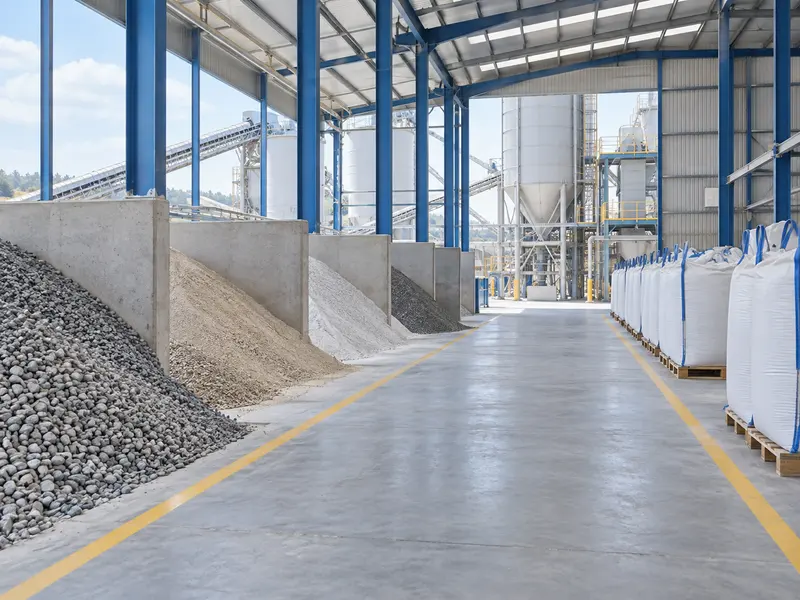
List the usable opening stock of each material and its purchase conditions. Consider delivery frequency, minimum order size, storage limits and the time needed to replace a rejected shipment. Apply the actual recipe and planned trial quantities instead of assuming that steady production consumption begins on the first day.
A large opening order may reduce freight per unit but also consume cash and storage space. Compare that saving with the flexibility of smaller deliveries while the recipe and production schedule are being established. Confirm whether supplier credit starts at dispatch, delivery or invoice acceptance.
Material Inside the Process
Track batches that have entered production but are not yet saleable. This includes material awaiting processing, curing, inspection or disposition after a quality concern. Its cash cost has already started even though the sales team cannot necessarily release the product.
Do not value all early output as finished inventory at the expected selling price. Separate accepted product, quarantined stock and rejected material, with treatment agreed by the finance and production teams. A realistic loss allowance belongs in the cash forecast because another batch may be needed to fulfil the same order.
Saleable Blocks in the Yard
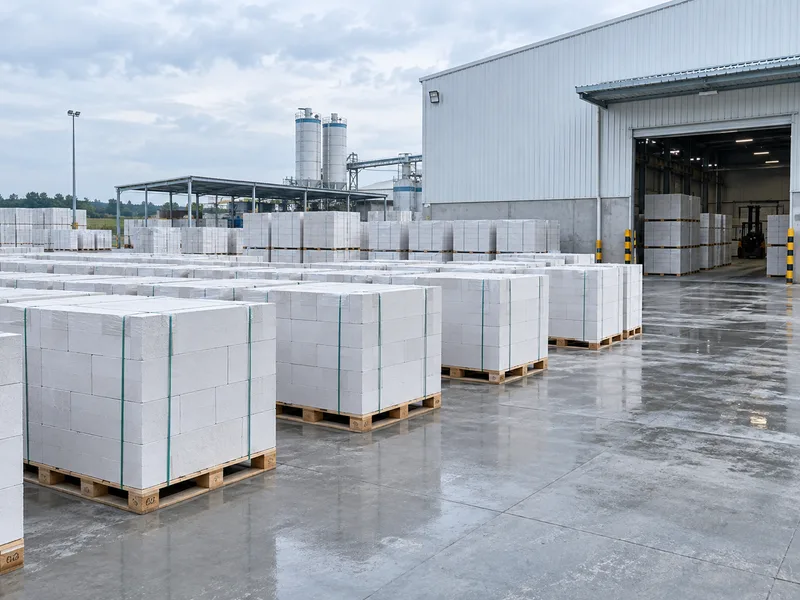
Opening finished stock should reflect the products customers are likely to order, not simply the easiest sizes to manufacture. Record quantities by product and age, including stock already allocated to a customer. Slow-moving sizes can occupy yard capacity while popular sizes remain unavailable.
Include packaging materials, essential consumables and the operating portion of the spare-parts stock. The AAC spare-parts planning guide helps distinguish critical availability from indiscriminate purchasing. Stock purchased with the equipment package must not be charged again as a separate opening cash payment.
Turn the Production Plan Into Weekly Payments
Start with a schedule of shifts, batches and accepted output. Show the expected ramp-up explicitly, including training, stoppages and quality release. Apply material purchases and operating payments to that schedule using their actual due dates.
A utility expense may be recorded in one week and paid in another. A transport contractor may require payment on dispatch even where the customer receives credit. These timing differences are central to the funding calculation and should not disappear inside an average monthly cost.
| Cash Line | Timing Evidence | Ramp-Up Question |
| Raw-material purchases | Order quantities and supplier due dates | Must stock be paid before usable output is available? |
| Payroll and site overhead | Payroll calendar and service agreements | Which costs continue during a production delay? |
| Energy and process services | Deposits, billing periods and payment terms | Are start-up deposits separate from consumption charges? |
| Packaging and dispatch | Shipment plan and carrier terms | Does payment precede customer collection? |
| Customer receipts | Acceptance, invoicing and realistic collection dates | What could delay a valid invoice or payment? |
Keep recoverable taxes, duties, deposits and refunds visible according to local arrangements. A recoverable amount may still create a temporary cash requirement. Use the responsible accountant’s treatment and expected recovery date, rather than assuming every tax payment is immediately offset.
Separate a Dispatch From a Receipt
For every early customer, identify the event that starts the payment clock. The event could be an advance payment, delivery, signed acceptance or submission of a complete invoice package. If missing documentation delays that event, adding the stated credit period to the shipment date will understate the cash gap.
Forecast collections by customer or customer group where payment behavior differs materially. Include disputed quantities, retention arrangements where applicable and the time taken to resolve delivery claims. An optimistic sales target should not automatically become a fully collected receivable.
Customer deposits can reduce the gap, but they are commitments to fulfil orders. Keep the associated production and delivery spending in the same forecast. Do not count an advance once as financing and again as a later sales receipt.
Locate the Lowest Cash Point
The following example uses arbitrary currency units to illustrate timing only. It excludes capital expenditure, taxes and debt service, and assumes zero opening cash solely to reveal the operating funding gap. Actual plant budgets require a more detailed schedule.
| Period | Cash Receipts | Operating Payments | Cumulative Balance |
| Pre-start | 0 | 80 | -80 |
| Week One | 15 | 45 | -110 |
| Week Two | 30 | 50 | -130 |
| Week Three | 55 | 50 | -125 |
| Week Four | 70 | 55 | -110 |
The deepest operating shortfall in this limited example is 130 units at the end of week two. That is the modeled funding gap before a contingency reserve or any excluded payment. A positive weekly movement in week three does not repay the earlier cash already committed.
Extend the forecast until collections and operating payments settle into a sustainable pattern. A four-week table is useful for explanation but may stop before the real low point. Large customer credit periods, seasonal demand or delayed acceptance can move that point much later.
Stress the Assumptions That Move Cash Most
Test slower accepted-output growth, later collections and a higher material requirement per saleable unit. Also consider a delayed utility connection or acceptance milestone that leaves payroll and overhead running. Change the drivers explicitly so the team can see which event consumes the reserve.
Check these scenarios against the commissioning and production acceptance plan. The commercial forecast should use the same readiness assumptions as the technical team. Conflicting start dates can create a funding gap before the first saleable batch.
Size the contingency around plausible disruptions and available responses, rather than hiding it inside inflated material costs. Record what spending could be deferred, which supplier terms are confirmed and which facilities are actually available. Unapproved credit should not be treated as cash already secured.
Run a Weekly Cash Review During Ramp-Up
Update the forecast with actual receipts, purchases, accepted output and stock age each week. Explain the difference between planned and actual cash using operational causes. This gives managers a specific response, such as adjusting a slow-selling product run or resolving an invoice acceptance problem.
Assign owners to the major assumptions: production yield, purchasing dates, dispatch quantities and collections. Set escalation points before the balance approaches its minimum reserve. The useful result is a funded operating plan that can survive a credible delay while the plant earns repeat orders.